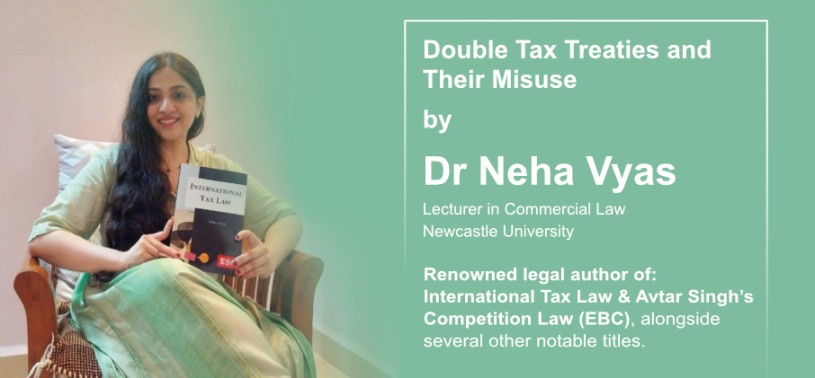
Double Tax Treaties exist to stop cross-border income from being taxed twice, but the same mechanics can be bent to achieve double non-taxation instead. Dr Neha Vyas, Lecturer in Commercial Law at Newcastle University and author of International Tax Law and several other well-regarded EBC titles, brings her characteristic clarity to this recurring problem, examining how treaty shopping and round tripping exploit the gap, and how recent developments like the Tiger Global ruling and the revised India–Sri Lanka DTAA are tightening the response.
Double Tax Treaties and Their Misuse
Cross-border income has a tax problem built into it: the country where it’s earned wants a share, and so does the country where the earner resides. Double Tax Treaties (DTAs) exist to stop that income from being taxed twice, so trade and investment don’t grind to a halt under two overlapping tax bills.
But there’s a catch. The same treaty mechanics that prevent double taxation can be bent to achieve the opposite i.e. double non-taxation. That gap between what a treaty is meant to do and how it actually gets used is where ‘treaty misuse’ lives, and it remains a live concern for tax authorities, multinationals, and investors alike.
1. The Function and Structure of a Double Tax Treaty
A DTA is a bilateral agreement between two states that determines which of them taxes a given stream of income like dividends, interest, royalties, business profits, and how much relief the other must grant where both have a claim on it.
It’s worth noting one nuance here that a treaty never creates a fresh tax liability. That always arises under domestic law. A treaty can only restrict how much of that liability a state collects from a cross-border taxpayer; it cannot confer a taxing right that did not already exist.
Most DTAs, whatever their country-specific variations, follow the same underlying structure drawn from the OECD Model Convention (which tends to favour the residence state) or the UN Model Convention (which allocates more to the source state). Both address the same essential ground: persons and taxes covered, allocation of taxing rights, relief from double taxation, dispute resolution, and increasingly safeguards against abuse.
2. Tax Planning, Avoidance and Evasion: Locating Treaty Misuse
Three terms are often used loosely, but they carry distinct legal meanings:
- Tax planning — lawful, and actively encouraged (using deductions, exemptions, and treaty credits exactly as intended)
- Tax avoidance — technically lawful, but structured against the spirit of the law rather than its letter
- Tax evasion — unlawful (concealment, fake invoices, undisclosed accounts)
Treaty misuse falls within the avoidance category. Its classic form is treaty shopping. It involves routing an investment through a jurisdiction with a favourable DTA solely to access benefits the investor would not otherwise qualify for, absent any genuine business presence there. Multinationals have historically used jurisdictions such as Cyprus, Mauritius, Singapore, or the Netherlands for this purpose, structuring cross-border holdings to secure reduced withholding tax on dividends, interest, and royalties.
A related device is round tripping, where domestic capital exits a country and re-enters disguised as ‘foreign investment’ through a shell entity, so that funds that are, in substance, domestic come to claim treaty exemptions intended for genuine foreign investors. India’s pre-2016 Mauritius route, which subsequently struck off via treaty amendment, remains the standard illustration in this area.
3. The Anti-Abuse Response: LOB and PPT
Modern DTAs, reshaped by the OECD’s BEPS project, now incorporate two layered defences:
- Limitation of Benefits (LOB) — a rules-based filter that confines treaty benefits to ‘qualified persons’ with genuine economic substance — bona fide businesses, listed companies, pension funds — while excluding shell entities with no operational footprint
- Principal Purpose Test (PPT) — a judgment-based rule denying benefits wherever it is reasonable to conclude that obtaining the benefit was one of the principal purposes of the arrangement, unless granting it would nonetheless accord with the object of the relevant treaty provision
The two operate in tandem. LOB addresses structural, readily identifiable cases, while the PPT supplies a broader standard for novel or sophisticated arrangements that escape a purely mechanical test.
Alongside these sits the role of tax havens and offshore financial centres that are low-tax, high-secrecy jurisdictions that frequently serve as the destination for treaty-shopping structures. The international response has been coordinated: the OECD’s BEPS Action Plans, country-by-country reporting, automatic exchange of information, and, within India, the General Anti-Avoidance Rule (GAAR), which empowers authorities to disregard “impermissible avoidance arrangements” irrespective of what a treaty permits on its face.
4. Recent Developments: Tiger Global and the India–Sri Lanka Protocol
Two developments from 2026 illustrate how this tension between treaty benefit and treaty misuse continues to play out in practice.
The Tiger Global ruling. On January 15, 2026, the Supreme Court delivered its verdict in Authority for Advance Rulings v. Tiger Global International Holdings arising from Tiger Global’s attempt to exit its decade-old Flipkart investment by selling shares in a Singapore entity, routed through Mauritius-based funds, while claiming exemption from Indian capital gains tax under the India–Mauritius DTAA. The Court sided with the tax authorities, holding that a valid Tax Residency Certificate is no longer sufficient by itself to claim treaty benefits, and that GAAR may override treaty protection wherever an arrangement lacks genuine commercial substance even for investments predating GAAR’s own commencement. The ruling is now the principal reference point for how far “form over substance” structuring can extend before it collapses under judicial scrutiny.
The India–Sri Lanka protocol. On the treaty-drafting side, a revised protocol to the India–Sri Lanka DTAA took effect on June 19, 2026, recasting the treaty’s preamble to state expressly that its purpose is to eliminate double taxation without creating opportunities for avoidance or evasion, and introducing a Principal-Purpose-Test-style anti-abuse clause directed squarely at treaty shopping.
Read together, the two developments show treaty misuse being addressed on both fronts judicially, after the fact, and through treaty drafting, in advance.
5. Situating the Discussion
This is only the surface. The interaction between LOB and PPT on a given set of facts, the application of Article 24 non-discrimination and Article 26 information-exchange in decided Indian disputes, the mechanics of the Mutual Agreement Procedure, and the full anatomy of tax havens and offshore structuring warrant closer treatment than a blog post can responsibly provide.
👉 Get International Tax Law by Dr Neha Vyas
For law students, researchers, and practitioners seeking a rigorous account of how treaties are misused and why the anti-abuse rules are drafted as they are, this is the natural next read.